Home  /  HELOC

Home Equity

A Fast Home-Equity Line of Credit, Applied for Online.

Through Ease Mortgage, you can apply online for a home-equity line of credit. Shane Thomas, Senior Loan Officer, can help you compare a HELOC with a cash-out refinance and decide whether to apply.

Funding may be available in as few as 5 days. Timing varies and depends on approval, verification, and the property.

The application is through Ease Mortgage’s HELOC platform. Not all applicants qualify. All loans are subject to credit and property approval. Terms are subject to change. A HELOC uses your home as collateral; if you cannot repay, your home may be at risk. This website is for education and is not an offer to lend. Shane Thomas is a Senior Loan Officer with Ease Mortgage, NMLS #444451. Ease Mortgage, NMLS #2273319.
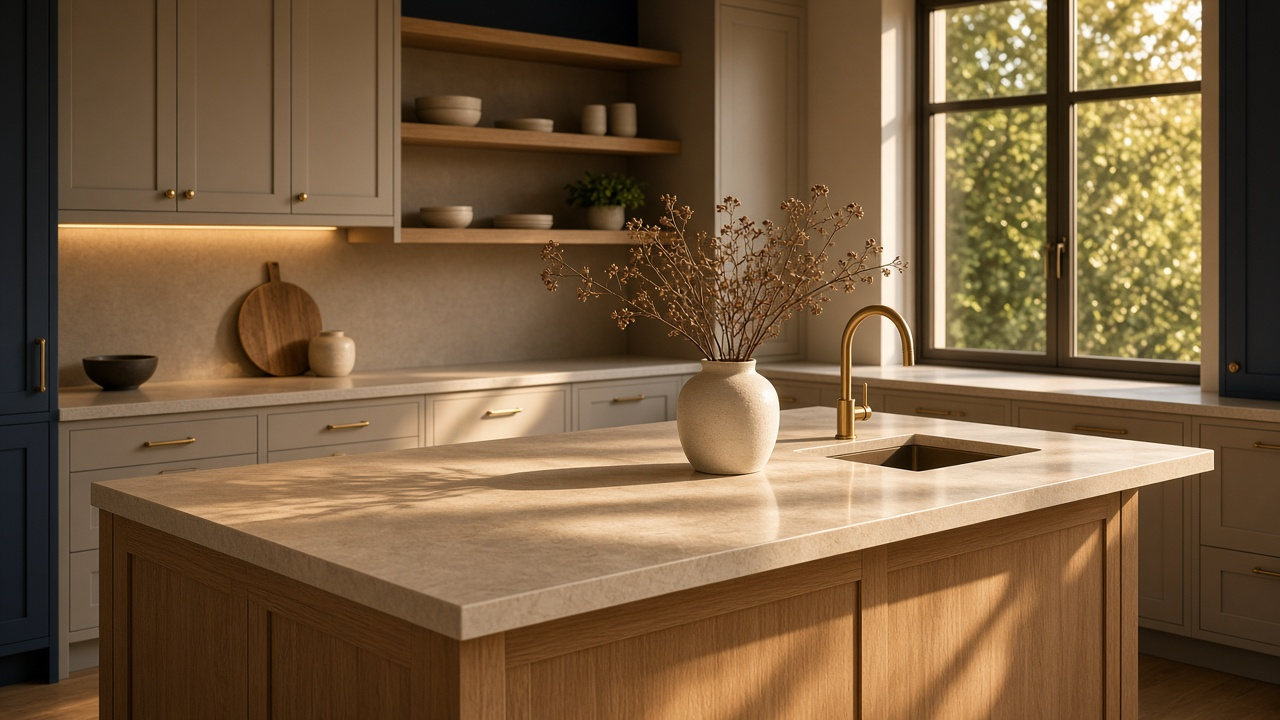
A renovated kitchen at golden hour with a white-oak island, warm window light, and navy cabinetry. Generated illustration, not a specific listed property.
How it works

Apply online, get a decision, sign, and get funded.

These are the usual steps on Ease Mortgage’s HELOC platform. Your path can differ based on approval, verification, and the property.

  1. Apply online

    Start a HELOC application through Ease Mortgage’s HELOC platform. You can also call Shane first if you want to talk through a HELOC versus a cash-out refinance.

  2. Get a decision

    The application is reviewed. Not all applicants qualify. Any decision is subject to credit and property approval, and to verification of the information you provide.

  3. Sign

    If you are approved and choose to move forward, you sign the loan documents. Closing details depend on the property and the transaction.

  4. Get funded

    Funding may be available in as few as 5 days. Timing varies and depends on approval, verification, and the property.

Common uses

Home improvement, debt consolidation, and other large expenses.

These are common reasons homeowners look at a HELOC. This is education, not a recommendation to use your equity for any particular purpose.

  • Home improvement

    A remodel, a repair, or another project on a home you already own is a common reason to look at a home-equity line of credit.

  • Debt consolidation

    Some homeowners consider using a HELOC to pay off other balances. A lower payment can look attractive, but it can also last longer and cost more overall — and it turns unsecured debt into debt secured by your home.

  • Large expenses

    Homeowners also use home equity for education, a major purchase, or another sizable cost. Using that equity puts your home at risk as collateral.

A comparison Shane often walks through

HELOC or cash-out refinance?

Neither option is automatically better. The better fit depends on your current loan, how you want to use the funds, and what you qualify for. Shane regularly compares these two paths with homeowners.

A HELOC may be a fit when

  • You want to use home equity without replacing your current first mortgage.
  • You want a separate home-equity line, with features that vary by product and approval, rather than a new first mortgage on the full balance.
  • Keeping your existing first-mortgage rate and term is part of what you are weighing.

A cash-out refinance may be a fit when

  • You want a single new first mortgage that replaces the loan you have now.
  • You want a lump sum, and a new rate, term, and payment that apply to the entire loan, not only to the cash you take out.
  • Refinancing the full balance is part of the goal, after you weigh closing costs and the new term.

Qualification, terms, costs, and how funds are drawn all depend on the specific loan, the property, and approval. For an educational payment illustration using figures you enter, see the cash-out vs. HELOC calculator. That tool is not a quote. You can also start with what’s your home worth for an estimated-value overview.

Who it may fit

Homeowners with equity, comparing their next move.

A HELOC can be worth discussing if you already own a home, have equity, and want to compare a home-equity line with a cash-out refinance. It may not be a fit if you do not want to use your home as collateral, or if you would not qualify. Not all applicants qualify, and Shane is licensed to originate residential mortgage loans in Michigan and Indiana.

Questions homeowners ask

HELOC FAQ

How quickly can a HELOC fund?

Funding may be available in as few as 5 days. Timing varies and depends on approval, verification, and the property. It is not a guarantee. Closing details can also depend on the property and the transaction.

Who offers this HELOC?

The application is through Ease Mortgage’s HELOC platform. Shane Thomas is a Senior Loan Officer with Ease Mortgage, NMLS #444451. Shane Your Mortgage Guy is his educational website, not a separate lender.

Will I qualify?

Not all applicants qualify. A HELOC is subject to credit and property approval, and terms are subject to change. Shane can talk through your situation before you apply, or you can start an application on Ease Mortgage’s HELOC platform when you are ready.

What can I use a HELOC for?

Homeowners commonly consider a HELOC for home improvement, debt consolidation, or other large expenses. Using home equity puts your home at risk as collateral. This page does not recommend a particular use.

How is a HELOC different from a cash-out refinance?

A cash-out refinance typically replaces your current first mortgage with a new, usually larger first mortgage, and you receive the difference in cash after costs. The new rate, term, and closing costs apply to the entire loan. A HELOC typically leaves the existing first mortgage in place and adds a separate home-equity line. Product features, including how and when funds are drawn, vary by program and approval. Neither option is automatically better. Shane regularly walks homeowners through this comparison.

Are rates or loan limits listed on this page?

No. This page does not publish rates, APRs, loan limits, or fees. Terms depend on the date you apply, approval, and the property. Call Shane or start an application to see what may be available.

Does this website collect my HELOC application information?

No. The application button opens Ease Mortgage’s HELOC platform in a new tab. This website is not connected to that system and does not collect financial information for a HELOC application.

Last reviewed November 15, 2026.

Shane Thomas, Senior Loan Officer at Ease Mortgage

Meet Shane

A Senior Loan Officer, not a separate lender.

Shane Thomas is a Senior Loan Officer with Ease Mortgage. He helps Michigan homeowners understand their options — including a HELOC versus a cash-out refinance — and move through the process with a clear plan.

Ease Mortgage · NMLS #444451 · Ease Mortgage NMLS #2273319
Based in Troy, Michigan — 1050 Wilshire Dr, Suite 300, Troy, MI 48084
586-260-2289 · [email protected]